A buyer’s guide to the law that decides what can be built on a plot, and who gets to say so
Most people call it “the Physical Planning Act.” It hasn’t gone by that name since 2019. The statute now governing what you can build, where, and under what conditions is the Physical and Land Use Planning Act, No. 13 of 2019, which repealed the old Cap 286 and folded planning and land use control into a single law. The rename matters less than what changed underneath it: wider public participation, a longer list of developments that need sign-off before a single block is laid, and county governments holding the actual decision.
The Act’s stated purpose is broad by design; it sets out the procedures and standards for development control regulation of physical planning and land use, alongside a framework meant to ensure that investment in property benefits the communities it sits in.
What “development control” actually covers
Development control is the mechanism through which a county decides whether a specific piece of construction, subdivision, or land use change is allowed to go ahead. The objectives, as set out in the Act, are to keep physical development orderly, put land to optimal use, carry out approved plans as written, protect the environment, and promote public safety and public participation.
A county’s development control powers include:
These powers sit with the county precisely because Section 56 of the Act assigns development control to county governments, not to national ministries. Where you build is a conversation with the county your plot sits in, not a single national office.
What needs a permit before you touch the ground
The 2019 Act dropped the old “Class A / Class B” grouping and instead lists specific developments that require development permission. If your project falls into one of these categories, county approval has to come before work starts, not after:
The Act also draws a firmer line between commercial and industrial use, which settles a question that used to trip up applicants filing under the wrong land-use category.
Change of use: the step that catches buyers off guard
Land zoned for one purpose does not become available for another simply because a buyer intends to use it differently. Converting agricultural land to commercial use, for instance, is a formal change-of-use process, not a formality on a title deed.
The applicant advertises the intended change in two widely circulated newspapers, giving the public 14 days to raise objections. If no objections stand, a registered physical planner files a PPA1 application with the county, attached to a project brief that sets out the development plan and how competing interests in the property were considered.
For a buyer, the practical implication is timing: change of use is a planning process with a public-comment period, not a same-week administrative fee. Due diligence on a plot should confirm current zoning and use classification before agreeing a purchase price, not after.
Zoning and land use plans set the boundaries before you apply
Development permission is decided against a backdrop of land use development plans, prepared at national, county, inter-county, and local levels. These plans are meant to be integrated, and together they form the basis of how land in a given area is meant to be used. A plot’s zoning- residential, commercial, mixed-use, industrial, agricultural- comes from this planning layer, and it is what a county checks a development application against.
Special planning area designations, such as the Mukuru Special Area Zone, illustrate how a plan can set bespoke development conditions for a specific area: density limits, permitted uses, and infrastructure requirements that apply on top of the general county plan.
Building without permission
The Act is direct about the cost of skipping this process: development permission must be obtained before work begins, and a developer who proceeds without it risks criminal sanctions and demolition of the unapproved works.
Regulators treat approved-but-not-followed conditions the same way as no approval at all. Extra units added beyond what was approved, encroachment into a road or riparian reserve, and ignoring building lines and setbacks are the recurring reasons cited when county governments order demolition, even where a project once held a valid permit.
What this means for a buyer or investor
None of this is a reason to slow down a genuine purchase. It is a reason to ask specific questions earlier than most buyers think to:
A title deed confirms ownership. It does not confirm that a structure was built where, how, or as high as it was approved to be. That confirmation sits with the county’s development control record, and it is worth requesting before, not after, a sale agreement is signed.
What sellers need to know
Selling a property in Kenya sets off two separate obligations: agreeing on a price with a buyer, and settling what the taxman is owed on the difference between that price and what the property cost you. The second obligation is Capital Gains Tax, and it is due before the transfer can even be registered. A seller who has not planned for it can find the sale stalled at the finish line.
What Capital Gains Tax actually taxes
Capital Gains Tax, or CGT, is charged on the profit made when property, land or unquoted shares change hands in Kenya, and it is administered under the framework that the Kenya Revenue Authority sets out for CGT. It is a tax on the gain, not on the sale price; if a property is sold at a loss, no CGT arises. The seller, referred to as the transferor, carries the obligation to declare and pay it, not the buyer.
The current rate
CGT in Kenya is charged at 15% of the net gain on a property transfer. It is a final tax, meaning once it is paid, that gain is not taxed again elsewhere. The net gain is the transfer value, less incidental costs of the transfer, less the adjusted cost of the property, being acquisition cost, incidental acquisition costs, and any enhancement or improvement costs.
A worked example
Take a seller who bought a plot in 2019 and is transferring it now. The numbers below show how the net gain and the tax on it are actually arrived at.
|
Item |
Amount |
|
Sale price |
KES 12,000,000 |
|
Acquisition cost (2019 purchase price) |
KES 7,500,000 |
|
Incidental costs (legal fees, valuation, agent commission on purchase and sale) |
KES 850,000 |
|
Net gain |
KES 3,650,000 |
|
Capital Gains Tax at 15% |
KES 547,500 |
What counts as a deductible cost
The gain is calculated after allowable expenses are subtracted, so keeping records of these from the day of purchase pays off at the point of sale:
When a sale is exempt
Not every transfer attracts CGT. The exemption sellers ask about most often is the private residence exemption: a property is exempt if the owner has occupied it continuously for the three years immediately before the transfer. Other exemptions cover transfers between spouses, transfers to immediate family, transfers as part of a divorce settlement, and transfers by a personal representative to a beneficiary in the course of administering a deceased person’s estate.
How and when it gets paid
CGT is declared and paid through iTax, and it falls due at whichever comes first: the seller receiving the full purchase price, or the transfer instrument being registered in the buyer’s favour. In practice, this means the tax is settled as part of closing, not afterward, and a completed transfer is not registered until it is.
Why this matters before a sale is priced
Sellers who treat CGT as a closing-day formality often discover the acquisition cost and improvement record they need are incomplete. Establishing the adjusted cost base early and confirming whether an exemption applies changes what a sale actually nets, and it changes it before an asking price is set rather than after an offer is accepted.
Stamp duty is the single largest one-off cost a buyer pays on top of the purchase price itself, and it is also the one most first-time buyers underestimate. It isn’t hidden; it’s a matter of public record, but it rarely appears on the price tag shown during a viewing, which is exactly why it catches so many buyers scrambling for extra cash right at the point of transfer.
What Stamp Duty Actually Is
Stamp duty is a tax charged on the legal instrument that transfers property from seller to buyer, collected by the Kenya Revenue Authority under Section 2 of the Stamp Duty Act, Cap 480. It isn’t optional, and it isn’t negotiable between buyer and seller; it’s a statutory charge, and the transfer document itself has no legal force until it’s paid.
How Much It Actually Costs- and a 2024 Change Worth Knowing
The standard rate is 4 percent of the property’s value for land classified as urban, and 2 percent for land classified as rural or agricultural. Where this gets less straightforward is that the boundary between “urban” and rural” has shifted: a directive from the Principal Secretary for Lands in April 2024 formally reclassified a long list of gazetted towns and municipalities, including areas in Kiambu, Ruiru, and Thika previously treated as rural, to the 4 percent urban rate. A buyer who assumes a peri-urban plot still qualifies for the lower rural rate, based on how the area was classified a few years ago, can end up budgeting for half of what they actually owe. Confirming current classification with the relevant land registry, rather than assuming based on how a location “feels”, is worth doing before finalizing a budget.
What the Rate Is Actually Calculated On
Stamp duty is not calculated on the price in the sale agreement. It is calculated on the property’s determined market value, which is why the process always involves a government valuation step before the final figure is known. If the government valuer’s assessed figure comes in higher than the agreed purchase price, stamp duty is charged on the higher figure, not the lower one a buyer negotiated. This is a common source of budgeting surprise: a buyer who negotiates a good price on paper can still owe stamp duty calculated against a materially higher official valuation.
The valuation itself isn’t something a buyer commissions privately and submits. It’s carried out, or verified, by the Chief Government Valuer or a valuer they’ve designated, specifically to establish the property’s true open market value for stamp duty purposes, separately from any valuation a bank might have ordered for mortgage approval, and separately from whatever figure a selling agent quoted during marketing. A buyer relying on a bank’s mortgage valuation or an agent’s asking price as a stand-in for the government figure can end up with a materially wrong budget, since these three numbers frequently diverge.
Stamp Duty Isn’t the Only Closing - Just the Biggest One
It’s easy to treat stamp duty as the whole story of what a transfer costs beyond the purchase price, but it’s really the largest line item in a longer list. Legal fees for the conveyancing advocate, land registry and registration charges, the cost of the government valuation itself, and in some cases survey fees all sit alongside stamp duty as separate, additional costs. None of these are optional extras a buyer can skip by using a different process; a property transfer in Kenya legally requires a licensed advocate to prepare and register the documents, so budgeting for stamp duty in isolation, without the costs that travel alongside it, still leaves a buyer short at completion.
Who Pays It, and When
The buyer pays. This is standard practice in Kenyan property transactions, and it isn’t something a sale agreement typically reassigns. Once the transfer instrument is assessed, payment is due within 30 days of assessment for locally prepared instruments, or within 30 days of receipt for documents executed abroad. That window is shorter than it sounds once conveyancing, valuation scheduling, and fund transfers are factored in, which is exactly why the money needs to be set aside before the transaction reaches this stage, not scrambled for once the assessment lands.
What Happens If You Don’t Pay
This isn’t a fee a buyer can quietly skip or defer indefinitely. An unstamped transfer instrument is legally invalid, and any agreement signed between the parties becomes null and void and is inadmissible in court as evidence until the duty is paid. Missing the payment window doesn’t just delay the paperwork; it attracts a penalty of 5 percent of the assessed duty for every quarter it remains unpaid, which compounds quickly on a six- or seven-figure transaction. The property simply cannot be legally registered in the buyer’s name without this step being completed.
How to Actually Pay It
Payment is made through KRA’s iTax platform rather than at a bank counter or land registry desk. A buyer or their advocate logs into iTax, registers the payment under the Agency Revenue tax head with Stamp Duty as the sub-head, fills in the transfer and valuation details, and generates a payment slip that can be settled via bank transfer or M-Pesa. This is generally handled by the conveyancing advocate as part of the transfer process rather than something a buyer does entirely alone, but knowing the mechanics helps a buyer follow along and confirm the payment has actually cleared before assuming the transfer is complete.
The Exemptions, and Why Most Buyers Won’t Qualify
A handful of exemptions exist, but they’re narrower than buyers sometimes assume. The recognized categories are transfers of property between spouses, transfers of family property to surviving members on the death of the person in whose name it was registered, and gifts of land to registered charitable organizations. There is no general first-time buyer exemption in Kenya’s standard property market; a first apartment purchase through an ordinary sale agreement attracts stamp duty at the full standard rate, the same as any other buyer. Exemptions also aren’t automatic even where a buyer genuinely qualifies; they require an application and approval before payment, not a claim made after the fact.
How to Budget for It, Concretely
· Estimate on the higher end: use the government valuation as your working assumption, not the price you negotiated, since the two can diverge
· Confirm the classification of the specified location before assuming the rural rate applies, particularly in fast-growing peri-urban areas in Nairobi
In Summary
Stamp duty isn’t a fee that can be negotiated away or quietly avoided; it’s a statutory cost that determines whether a property transfer is even legally valid. Budgeting for 4 percent of a property’s likely government valuation, rather than 4 percent of the negotiated price, confirming the area’s current classification before assuming a rate, and setting stamp duty within the wider basket of closing costs rather than treating it as the only add-on are the adjustments that keep this cost from becoming a last-minute scramble.
Buying property in Kenya is one of the most significant investments you can make. Whether you are a first-time homebuyer in Kenya, a seasoned real estate investor, or someone simply exploring apartments for sale in Nairobi, understanding the land and sectional title process is crucial to ensuring your ownership is legal, secure, and hassle-free.
In this guide, we break down everything you need to know about landownership and the sectional title deed process in Kenya, including what they are, how they work, and how to protect your investment.
What is Land Ownership in Kenya?
In Kenya, land is classified into three categories:
When buying private land, whether it is an apartment, piece of land, or a townhouse, you receive a title deed confirming legal ownership.
There are two main types of land ownership:
What is a Sectional Title?
A sectional title is a form of property ownership that allows an individual to own an apartment or unit in a multi-unit building (a block of flats), while sharing ownership of the common areas (e.g. elevators, parking lots, and staircases).
Sectional Properties Act (2020) regulates the legal framework for sectional ownership in Kenya.
This is especially relevant for buyers looking for:
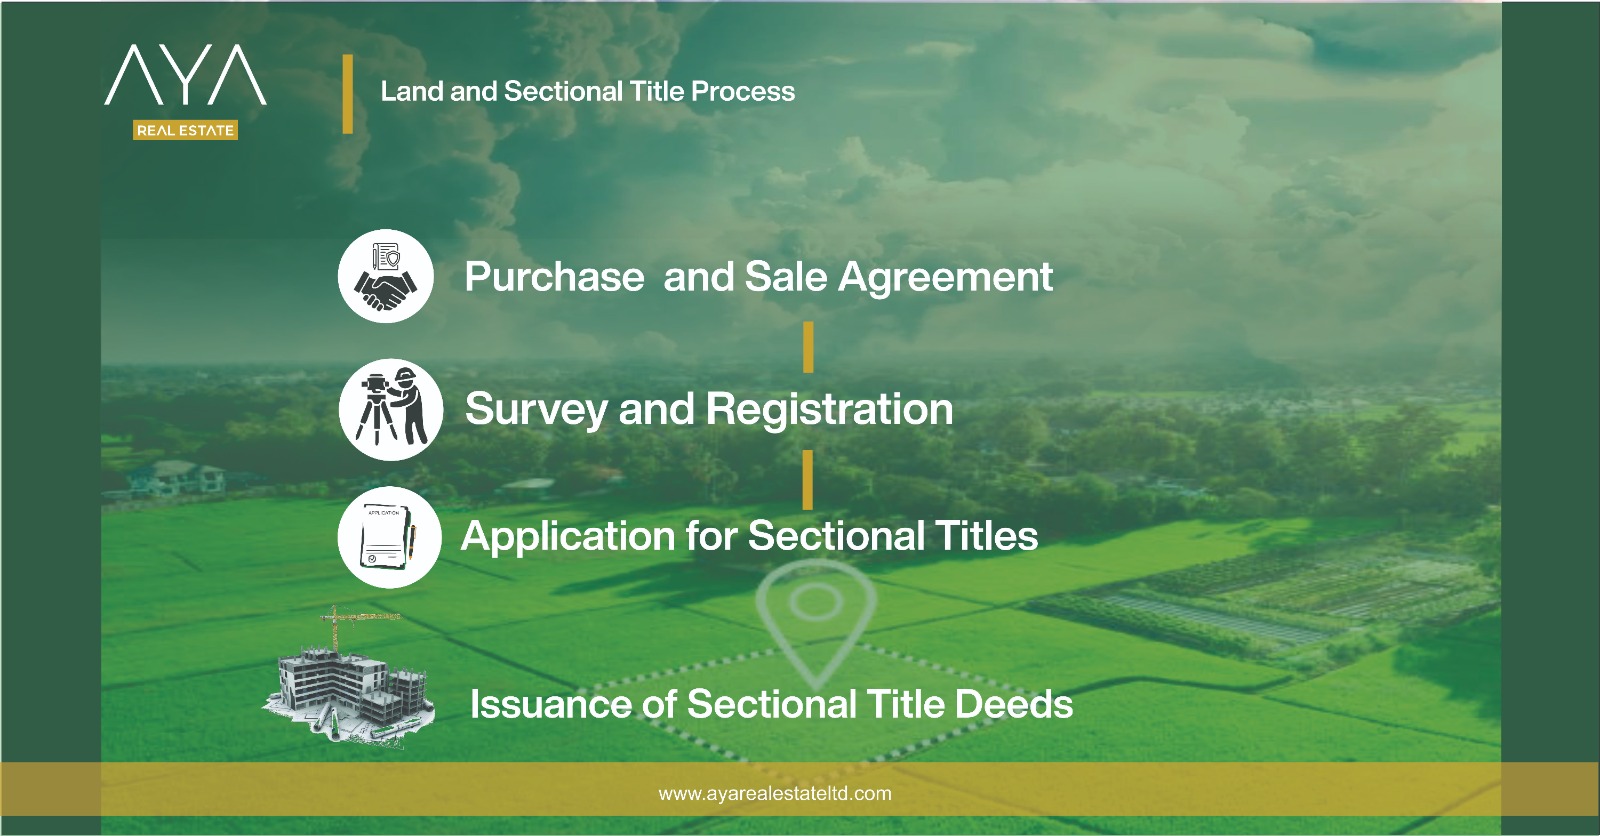
The Sectional Title Deed Process in Kenya
1. Purchase and Sale Agreement
Once you identify your preferred unit (e.g. a 2-bedroom apartment with amenities like a gym or swimming pool), a sale agreement is signed between you and the developer or seller. Ensure a licensed real estate agent in Kenya is involved.
2. Survey and Registration
The building is surveyed, and the units are geo-referenced into sectional plans. The plans are registered with the Ministry of Lands.
3. Application for Sectional Titles
The developer applies for sectional title deeds. This replaces the mother title of the whole land parcel with individual unit titles.
Upon approval, each unit owner receives an official sectional title deed, legally confirming your ownership of the specific unit and your share in the common property.
Many buyers wrongly assume that buying an apartment comes with a title deed automatically. Without sectional title registration, you may only hold a lease or share certificate, not full ownership.
A registered sectional title deed gives you:
When buying apartments in Nairobi, these common amenities fall under shared ownership and maintenance:
This makes sectional title ownership ideal for buyers looking for luxurious and secure apartments in Kenya without owning an entire block.
1. Confirm Developer Compliance
Ensure the project is compliant with the Sectional Properties Act and that sectional plans are registered.
2. Understand Ownership Costs
Expect service charge payments for maintaining shared areas.
3. Hire Legal Experts
Always work with a property lawyer to verify documentation.
4. Ask for the Title Number
Verify that the unit has an independent title number from the Land Registry.
Sectional titles have opened up affordable homeownership and real estate investment opportunities for middle-income earners.
They’re common in:
By clarifying ownership and simplifying management, they provide buyers with more security and value; especially in places like Nairobi, Mombasa, and Kisumu.
Understanding the land and sectional title process in Kenya is not just legal due diligence, it's smart investing. As more Kenyans turn to apartments and off-plan homes, sectional title deeds are the future of secure and transparent ownership.
Whether you’re buying your first home or adding to your investment portfolio, make sure your apartment comes with a sectional title. It’s your proof of ownership, your key to resale value, and your shield against disputes.
At AYA Real Estate, we help you navigate Kenya’s property market with clarity and confidence. From off-plan apartments in Nairobi to fully serviced modern units with gyms, elevators, and ample parking. We guide you every step of the way.
Contact AYA today for site visits, title verification, or to book your next apartment.
Let’s make homeownership easier, safer, and smarter.
Let’s get you started.
Call us today or DM to schedule a site visit.
Call: 0114 000 444/ 0752 000 444
Email: info@ayarealestateltd.com
Visit: www.ayarealestateltd.com